- How to Build an Investment Plan That Actually Works for You?
- What Is the MACD Indicator and How to Use It
- What Is a Wedge Pattern in Trading?
- What Is Ichimoku Cloud Strategy? A Complete Trading System
- Mastering Elliott Wave Theory: Rules and Trading Strategies
- News Trading: Strategies, Execution Risks, and Risk Control
- What Is an Iron Condor Options Strategy?
- Backtesting Explained: What It Is and Why It Really Matters
- Grid Trading: Mechanics, Parameters, and Risk Strategies
- What Is Breakout Trading and How Does It Work?
- Mean Reversion: Technical Strategies and Risk Frameworks
- Momentum Trading: Indicators, Strategies, and Risk Control
- Hammer Candlestick: Structure, Meaning, and Strategy
- Doji Candlestick: Types, Signals, and Trading Strategies
- What Is the Sharpe Ratio and How to Calculate It
- What Is VWAP and How Do Traders Use It?
- Trade the Ascending Triangle: A Step-by-Step Practical Guide
- What Is the Stochastic Oscillator and How to Use It
- How to Trade the Descending Triangle Pattern
- High Frequency Trading: Speed, Algorithms, and Market Impact
- What Is Volume Profile and How to Use It in Trading
- What Is a Morning Star Pattern Candlestick?
- Trade with Parabolic SAR: A Practical Analysis Guide
- Evening Star Pattern: Structure, Rules, and Risk Controls
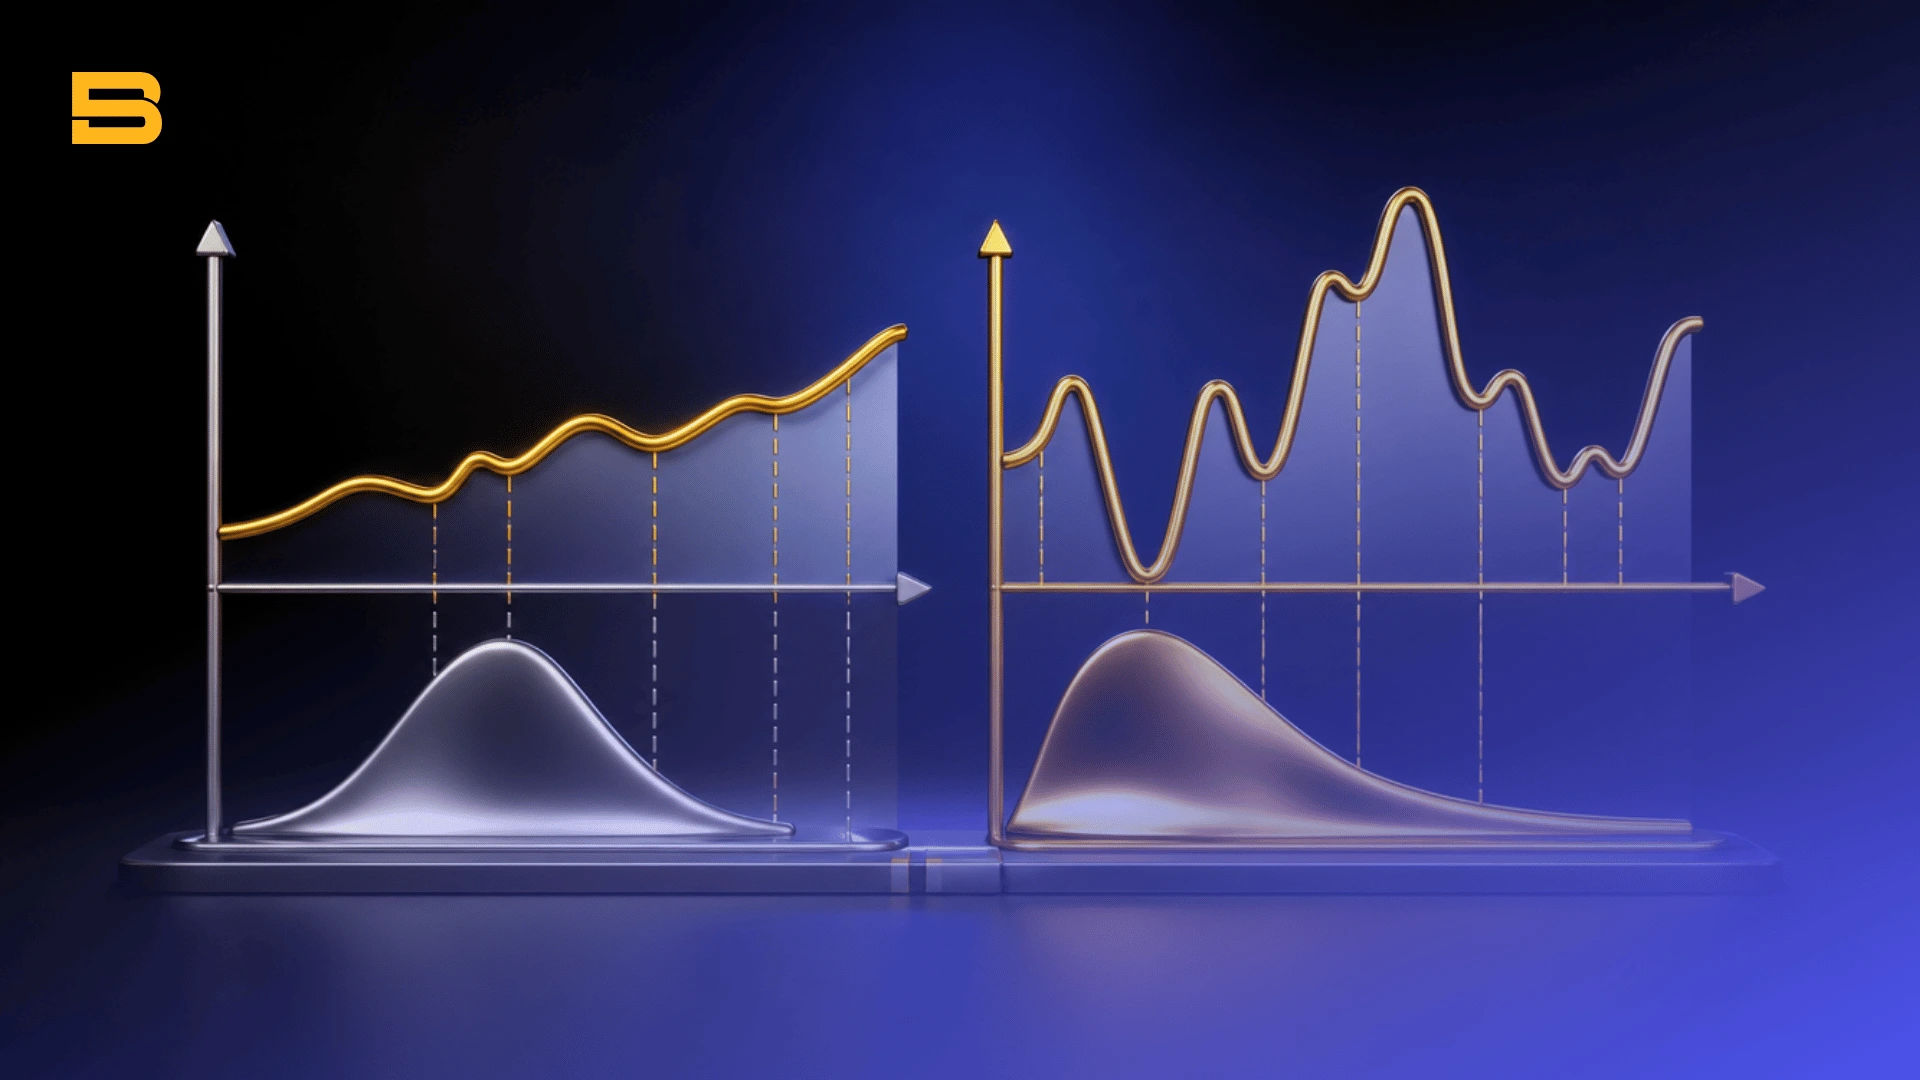
Imagine two quantitative trading strategies that both generate a 15% annual return. The first strategy achieves this return through steady gains with occasional shallow pullbacks, while the second strategy experiences violent upward spikes alongside sharp drops.
Traditional performance metrics often grade both strategies identically because they only measure total price variance. To evaluate how effectively a portfolio manager generates excess return without penalizing upside momentum, active traders rely on downside risk analytics.
What Is the Sortino Ratio and Why Downside Risk Matters
The Sortino ratio is a risk-adjusted performance metric that measures portfolio return relative to negative volatility by isolating downside price fluctuations from total market variance.
Developed by economist Frank A. Sortino, this metric addresses a fundamental flaw in traditional risk accounting. Standard portfolio variance models treat all price deviations equally, counting large upward price moves as negative risk factors.
For asymmetric trading strategies such as trend-following or buying long options, large positive spikes are desirable outcomes rather than risk indicators. Standard variance metrics penalize these strategies for achieving explosive upside growth.
By focusing exclusively on harmful volatility, the Sortino ratio provides a clearer picture of capital preservation. Traders use this measurement to determine whether excess returns stem from disciplined market positioning or unnecessary exposure to severe tail-risk events.
The Sortino Ratio Formula Explained
Calculating the Sortino ratio requires isolating negative asset returns relative to a targeted benchmark threshold.
The mathematical formula for the Sortino ratio is expressed as:
S = (Rp − MAR) ÷ σd
Where:
- Rp = Expected portfolio or asset return
- MAR = Minimum Acceptable Return (also referred to as the target hurdle rate)
- σd = Downside deviation (the standard deviation of negative returns)
Institutional standards established by bodies like the CFA Institute emphasize evaluating performance metrics on a standardized risk basis to avoid misleading risk-adjusted comparisons.
Risk-Free Rate vs. Minimum Acceptable Return (MAR)
While traditional metrics default to the government treasury yield as their benchmark baseline, the Sortino ratio utilizes the Minimum Acceptable Return (MAR).
Traders can set the MAR equal to the risk-free rate, zero percent, or a specific corporate hurdle rate such as 8% per annum. Setting an ambitious MAR raises the evaluation threshold, requiring the trading strategy to generate higher net returns to achieve an acceptable score.
Understanding Downside Deviation (The Denominator)
Downside deviation (σd) serves as the denominator in the formula, measuring only returns that fall below the chosen MAR.
The mathematical expression for downside deviation is calculated as the square root of: the sum, across all N evaluation periods, of the squared value of the lesser of zero or (the period's return minus the MAR) — all divided by N.
A critical detail in this calculation is dividing the sum of squared negative differences by the total number of periods (N), rather than only counting negative periods. This statistical structure ensures that periods with positive returns actively dilute total portfolio downside risk, accurately reflecting overall strategy stability.
Step-by-Step Calculation Example
To understand how downside deviation functions in practice, consider a 5-month trading sequence with an investor hurdle rate (MAR) of 0%.
Assume a trading portfolio produces the following monthly return series:
- Month 1: +8%
- Month 2: −3%
- Month 3: +12%
- Month 4: −5%
- Month 5: +4%
Step 1: Calculate Average Portfolio Return (Rp)
Rp = (8 − 3 + 12 − 5 + 4) ÷ 5 = 16 ÷ 5 = 3.2%
Step 2: Isolate and Square Negative Deviations Below MAR (0%)
- Month 1 (+8%): Return > MAR → 0
- Month 2 (−3%): (−3% − 0%)² = 0.0009
- Month 3 (+12%): Return > MAR → 0
- Month 4 (−5%): (−5% − 0%)² = 0.0025
- Month 5 (+4%): Return > MAR → 0
Step 3: Calculate Downside Deviation (σd)
- Sum of squared negative deviations: 0.0009 + 0.0025 = 0.0034
- Divide by total periods (N = 5): 0.0034 ÷ 5 = 0.00068
- Take the square root: σd = √0.00068 ≈ 2.6077%
Step 4: Compute the Final Sortino Ratio
S = (3.2% − 0%) ÷ 2.6077% ≈ 1.227
Evaluating this portfolio yields a Sortino ratio of 1.23.
By comparison, calculating the standard Sharpe ratio for this exact same dataset yields a score of 0.50. The standard metric penalizes the portfolio for its large positive months (+8% and +12%), whereas the Sortino calculation correctly recognizes that upward volatility does not increase downside risk.
Sortino Ratio vs. Sharpe Ratio: Key Differences
While both metrics measure risk-adjusted performance, their underlying mathematical assumptions create distinct analytical perspectives.
Traders evaluating leveraged derivatives or high-volatility strategies must account for capital preservation. High leverage magnifies both profits and losses equally, meaning a steep drawdown can trigger margin liquidation before a strategy has time to recover.
Sortino Ratio vs. Other Risk Metrics (VaR, Calmar, Treynor)
Portfolio analysts rarely rely on a single metric when building trading models or managing institutional capital.
Integrating multiple statistical dimensions yields a complete profile of strategy durability:
- Value at Risk (VaR): Estimates the maximum expected dollar loss over a specified timeframe at a defined confidence interval.
- Treynor Ratio: Measures excess returns per unit of systematic risk, utilizing the beta coefficient rather than total volatility.
- Information Ratio: Evaluates portfolio excess returns relative to a specific benchmark index divided by tracking error.
- Calmar Ratio: Compares annualized returns directly against maximum historical drawdown, focusing heavily on peak-to-trough capital decline.
When managing position sizing across asymmetric return profiles, quantitative systems often pair downside risk evaluation metrics with dynamic allocation algorithms like the Kelly Criterion.
How to Interpret Sortino Ratio Benchmarks
Understanding numerical outputs allows traders to benchmark trading models against institutional funds.
Baseline guidance published by international economic institutions such as the International Monetary Fund (IMF) highlights the importance of evaluating risk metrics across entire market cycles to prevent short-term statistical distortion.
A negative ratio indicates that the portfolio return fell below the target hurdle rate during the evaluation period.
Factoring Downside Risk
The Sortino ratio offers a refined perspective on portfolio performance by filtering out beneficial upside volatility. By measuring returns strictly against negative price movement, traders can distinguish between true strategy edge and dangerous tail-risk exposure.
Integrating downside analytics into your risk management framework ensures that capital allocation remains focused on long-term growth and capital preservation.
Disclaimer: The content on this page is intended for educational and informational purposes only. It does not constitute financial, investment, tax, or legal advice, and should not be interpreted as a recommendation to buy, sell, or hold any financial instrument or asset. Trading and investing involve significant risk, including the possible loss of your entire capital. Products such as forex, CFDs, and cryptocurrencies carry additional risks due to leverage, high volatility, and limited regulatory protection in some jurisdictions. Past performance of any financial instrument does not guarantee future results. Any market views, forecasts, or opinions expressed are those of the author at the time of writing and may not reflect current market conditions. Platform features, fees, and regulatory status are subject to change — always verify information directly with the relevant provider or regulator before making any financial decision. BrokerSpecs may receive compensation from third parties featured on this site. Always conduct your own due diligence and consider seeking advice from a licensed financial professional before investing.